Research article

Shopping Centre Investment

With 23 shopping centres currently under offer, and a further 44 in the market, the final quarter will be a busy one.

The shopping centre market in Q3 2015 has continued in the same strong vein as the last 18 months, with 18 deals completed, accounting for £1,172 million of transactions.

The statistics for the full year of 2015 now read as 55 deals transacted accounting for £3,047 million. This compares to £4,798 million at the same point in 2014 in 72 deals. However, when we consider the 23 shopping centres under offer equating to around £1,294 million and the fact that there are a further 44 schemes in the market totalling £2,173 million, the numbers are set to climb significantly in the final quarter.

Notably our figures do not include the Project Jewel (Dundrum, Swords, and Ilac) numbers which would add a further €1.85 billion to the totals. Project Jewel is currently under offer to Hammerson and Allianz but is excluded from our numbers as it is located outside the UK.

Should all the assets in the UK and Ireland that are under offer and those in the market complete, this would take the total investment volume for the year to around £7 billion, ahead of 2014 and significantly above the long term average.
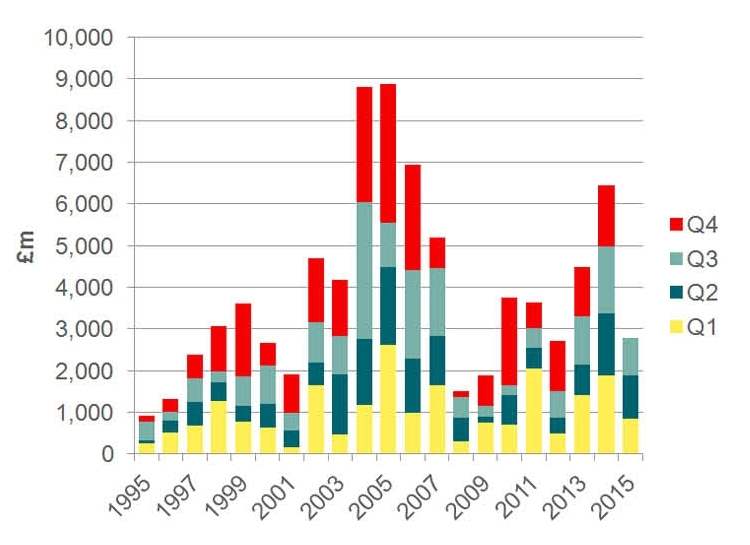
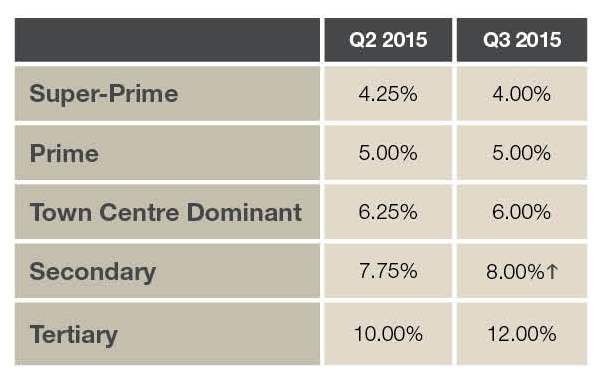
Figure 1

FIGURE 2Shopping centre investment volume

Source: Savills Research

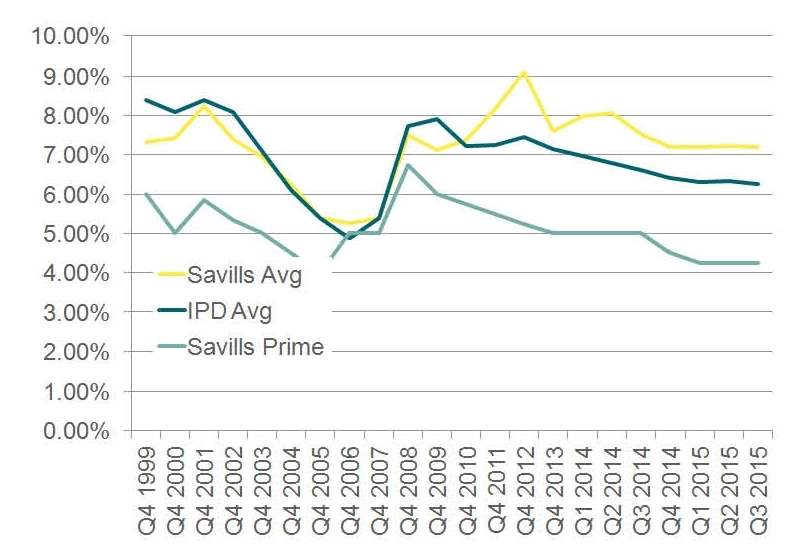
The average net initial yield in 2014 was 7.65% and so far this year it has nudged south of 7% and currently sits at 6.97%. This reflects the better quality of stock on the market and the continued demand for this asset class from investors.

Notable deals in Q3 include the sales of Angel Central in Islington for an initial yield (IY) of 3.9%, West One Shopping Centre on Oxford Street for an IY of 3.50% and Eastgate in Inverness for an IY of 6.75%. These transactions saw extremely strong bidding, which demonstrates the continued demand for London assets and assets which dominate their catchment. For the right assets there continues to be significant demand, leading to competitive bidding and values in excess of quoting.

Figure 2

FIGURE 3Shopping centre yields

Source: Savills Research

The secondary and tertiary markets are becoming increasingly constrained as investor appetite for risk seems to fall, whilst the leasing markets improve. Increasingly demand is more sensitive to geographical location, dominance, income profiles, asset management angles and unrealistic pricing expectations. Concerns are being raised that assets are being put to the market at overpriced levels and these over inflated values combined with the option to refinance are reducing fresh sales to the market. Some commentators and investors have stated that they are finding debt more difficult to obtain, but in many cases this is for those parties now looking to maximise their loan to value.

The secondary market has seen a shift from distressed sales, which are still well received by the market, versus those assets well managed by property companies and private equity houses looking to exit ahead of business plan. The nature of the sellers means that there are typically far fewer ‘asset management angles’ to model and the assets are generally perceived as relatively ‘dry’.

We are not anticipating a great deal of new stock coming to the market but we have already seen the likes of St Johns, Liverpool and St Enochs, Glasgow come to the market. As we come into the Autumn demand will continue to polarise with prime assets attracting significant interest and secondary shopping centres being received in a far less uniform, more selective manner.

Figure 3

FIGURE 4Shopping centre yields

Source: Savills Research

We are still anticipating that in excess of £5.5 billion will be transacted in 2015, well ahead of the long term average of £4 billion, but below the £6 billion in 2014 and our projections earlier in the year.

Income and its diversity is a massively attractive element of the shopping centre market and those parties who have lower return criteria, the right asset management skills and sensible debt aspirations will come to the fore in the secondary market going forward.

Other articles within this publication

3 other article(s) in this publication