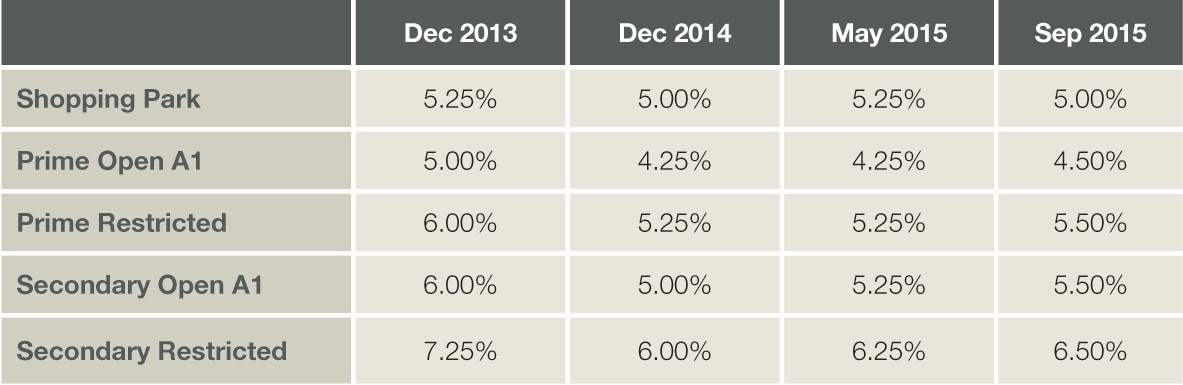
However, investor demand remains strong with institutional investors heavily biased towards the best schemes in the best locations.
Once again there have been and will continue to be very few high calibre schemes on the market, as these tend to be owned by the same handful of institutions that are currently trying to increase their holdings of retail warehousing. This has forced the institutional demand to stretch their buying criteria further down the qualitative spectrum.
As the level of demand has eased, it is apparent that the funds are not prepared to stretch this too far. This has led to the emergence of a "two-tier" market with strong demand for the very good assets and softening yields for poorer assets where investor demand is weaker.
Looking ahead we expect to see more opportunistic money entering the market in the final quarter of 2015 and into 2016. These investors are likely to be attracted by the higher yields on offer, as well as focusing on the secondary but still successful parks and schemes.
This could well be a very canny time to enter that segment of the market, as we believe that the recent softening in yields is only a temporary blip, and that the fundamentals of the sector will deliver good rental growth over the next five years. This will drive an improved return, with our five year forecast for retail warehousing returns remaining stronger than most other parts of the retail sector.