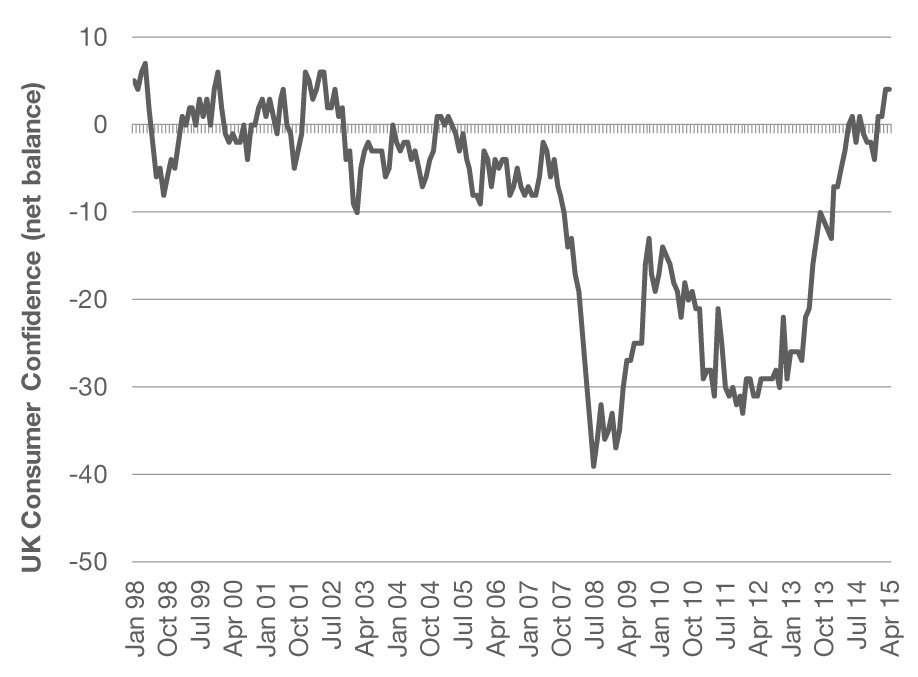
While retail sales dipped unexpectedly in March, primarily due to a fall in fuel sales, the volume excluding fuel rose by 0.2% month on month, and 2% quarter on quarter. Of course, a lot of this strong spending growth is being driven by heavy discounting across both the food and comparison goods sectors and this is by no means a sustainable strategy for retailers.
Ultimately the key metric for us this quarter remains the fact that the "noflation" is providing a substantial boost to household's spending power.
The low level of inflation, whether it is marginally positive or marginally negative, is very important in the current environment where earnings growth remains weak. Indeed, despite a further drop in unemployment, average weekly pay only rose by 1.3% in the year to February, well down on the levels seen last year.
We are forecasting that housing transaction levels will recover to around 1.3m a year in 2016, which while it is well behind the 2m turnover seen in 2004, is well up on the recessionary slump to 0.8m. There are obviously still concerns about the pace, if not the timing, of the inevitable rise in interest rates. However, we expect the rise to be gradual and over a long period, and this will not be enough to derail the consumer recovery.