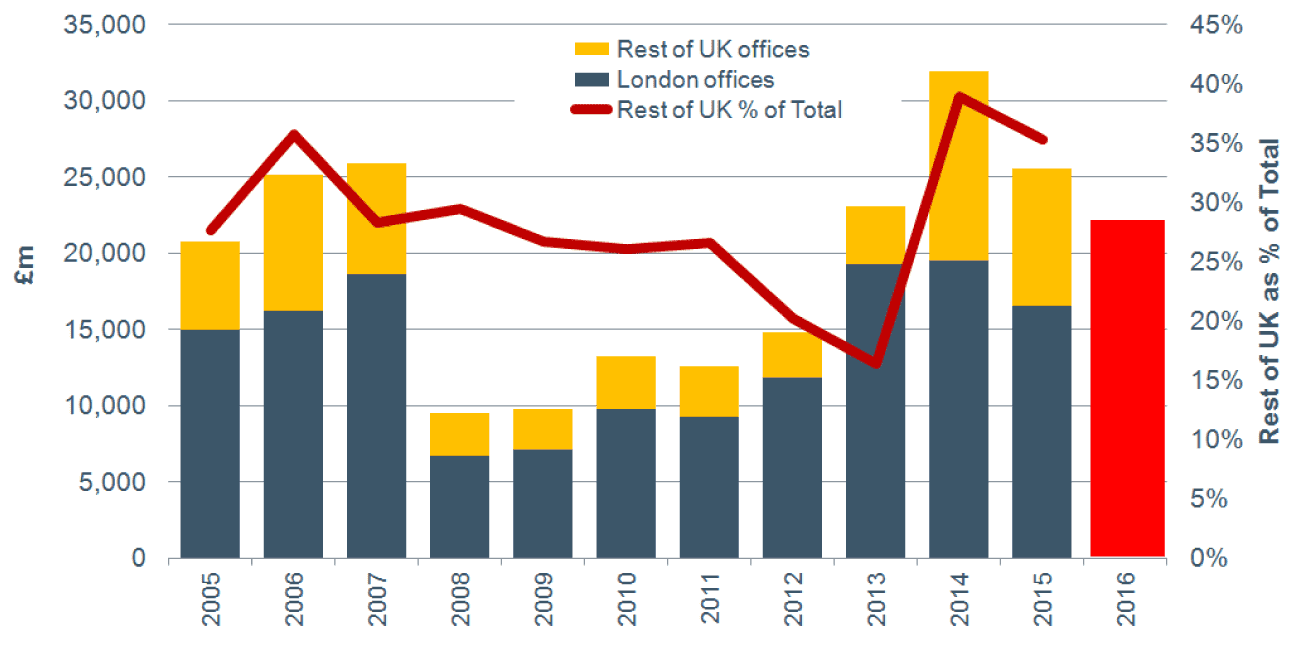
■ The proportion being invested in office markets outside London has risen over the last two years, with the proportion standing at 31% in 2015 (regional volumes only made up 16% of total volumes in 2013).
■ Birmingham's Colmore Plaza acquired by Ashby Capital for £140m, its first investment outside London, and 1 Colmore Square which sold for over £87m, well in excess of its initial asking price, demonstrates this regional appetite.
■ 2015 has been a 'happy hunting ground' for the institutions, who made up 35% of volumes in 2015, with deals such as Media City completing in 2015. The landmark sale of a 50% interest in MediaCityUK was sold for £503 million to Legal & General Capital. There was also significant international interest in this opportunity, which highlights the global strength of the regional markets.
■ Overseas buyers, attracted by the relative safety of investment in the regional office markets without the central London price tag, have made up 31% of regional office investment volumes in 2015.
■ 2015 saw some very high profile sales such as Deutsche Asset & Wealth Management’s acquisition of 2 St Peter’s Square, Manchester, from Mosley Street Ventures, for £100m. The building is due for completion this year, with Ernst and Young already secured as future tenants. We expect this overseas interest to continue as we go through 2016.
■ Deutsche Asset & Wealth Management also bought 110 Queens Street, Glasgow at the end of 2014, again, before it had completed construction, showing the improved confidence in the speculative market, as well as overseas interest in regional assets.
■ Arguably, UK funds, who are most comfortable with understanding the regional office market dynamics, have increased their appetite across the UK.
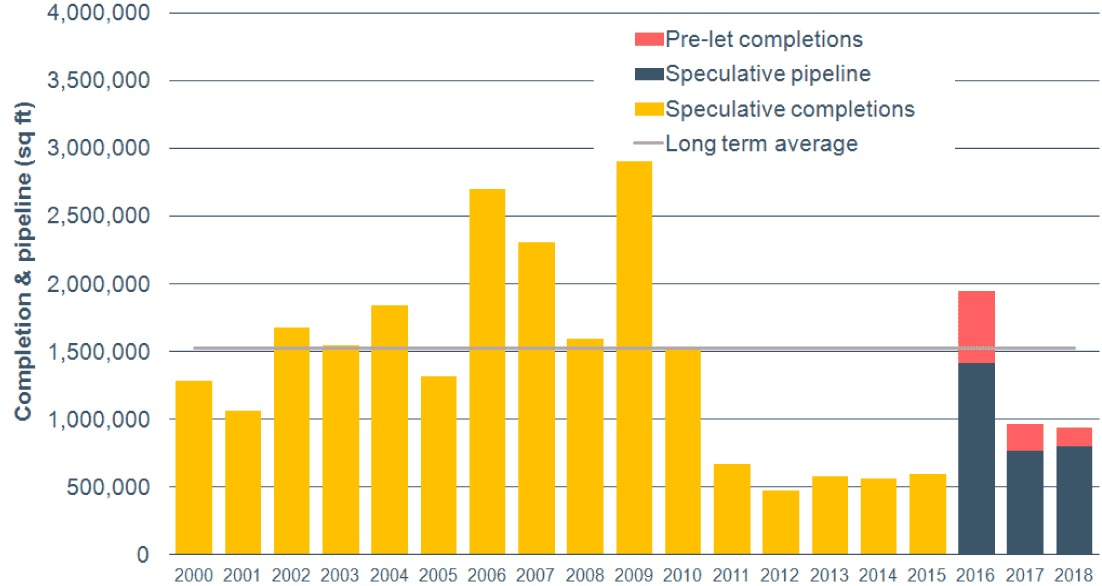
■ With institutions now having money for funding and with a restored market confidence and positive sentiment, large scale speculative developments have started to materialise.
■ Fund appetite for speculative development become apparent with Mountgrange’s 143,000 sq ft One West Regent Street, and BAM’s 163,000 sq ft 110 Queen Street in Glasgow completing in 2015. Other cities are now following suit. These include:
■ Central Square, Leeds, funded by M&G is a 220,000 sq ft development due for completion summer 2016, with significant pre-lets already in place.
■ The third phase of Ballymore Properties highly successful Snowhill scheme is another example. The first two phases have already drawn on occupiers including: Barclays, KPMG and Wragge Lawrence Graham & Co. We expect the third phase, which will provide Grade A office space of approximately 400,000 sq ft, to attract similar interest. We understand this is currently under offer.
■ As more institutional prime stock is developed out, the increased critical mass will widen the investment appeal to both UK Funds and more overseas investors.
■ There has also been a continued pick-up in investor demand for secondary assets in strong locations, where a successful refurbishment will lead to rental growth and significant increase in values as rent difference between new and refurbished has become marginal. A recent example of this is Circle Property's, acquisition of one of Birmingham’s key office refurbishment opportunities, Somerset House from M&G for circa £7.8m.
■ There has been a more pronounced depth of investment demand within the regional office sector, with healthy demand for well let Grade A stock, asset management opportunities further up the risk curve and, more recently, speculative development.
■ As we go through the first quarter of 2016, with inflows at a more manageable pace, we expect the funds to start focusing on their own portfolios, which is likely to bring more stock to the market.
■ In terms of investment volumes we expect 2016 to end the year above the long-term average but below the level achieved in 2015.
■ The 2016 investment market will be driven by the smaller end of the market rather than the larger trophy assets, as has been the case over the last two years. The next big opportunity may be to package up groups of smaller assets to create high quality regional portfolios, which are large enough to satisfy investment requirements.
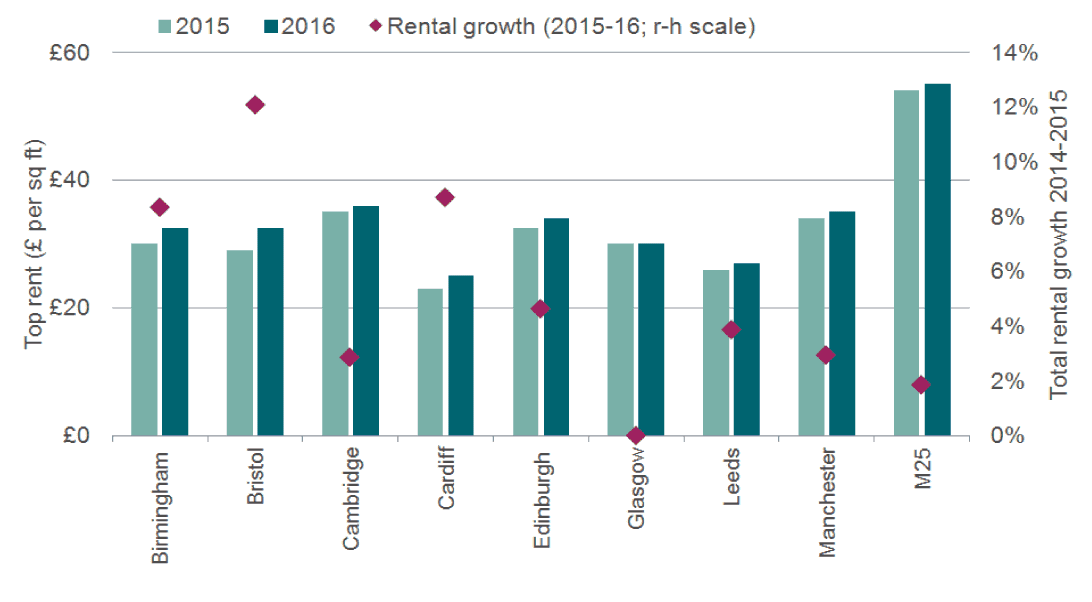
■ For UK property investment, at present, there is a higher degree of uncertainty, which may drag on the investment volumes during the first half of this year. However, there will be a desire amongst investors to capture the upswing in the regional leasing market, particularly as capital value growth prospects begin to slow.
■ We believe the early phase of recovery is now ending and we are now moving into the phase of the cycle where the majority of the total return will be driven by income return and rental growth, rather than just capital value growth.